Household costs in New Zealand depend on location, transport, household size and available income. A national price index shows broad price movement, not one person’s weekly bills.
Household costs, not national averages
Two households in the same New Zealand city can face different expenses because one rents a small flat near work while the other pays a mortgage, runs two cars and supports children or relatives. Income, housing tenure, health needs, age, transport access and family obligations all change the monthly picture. A national average is useful context; it is not a personal budget.
Household costs are easiest to understand when separated into fixed commitments, flexible spending and irregular bills. Rent or mortgage payments may be the largest fixed item, but transport, childcare and power can become equally significant for a particular household. Annual car registration, insurance renewals, school costs and appliance replacement often create a cash shortfall when they are not translated into weekly amounts.
Use take-home income rather than gross salary. PAYE, KiwiSaver contributions, student loan deductions, child support and benefit abatements can change the amount available for daily spending. A contractor’s income may arrive unevenly, so a monthly average can hide a lean week.
The biggest budget decisions are connected
Housing and transport should be assessed together. A cheaper rental outside a frequent bus corridor may require a second vehicle, extra fuel and more time. A home close to work and school can cost more per week while reducing daily travel. The relevant comparison is the total household routine, not rent alone.
Power costs depend on insulation, heating type, occupancy, appliance use and the structure of a retailer’s plan. A home that is difficult to heat can create discomfort and health pressure as well as a larger bill. When viewing a rental or home, ask about heating, moisture, insulation and past utility patterns where possible.
Inflation versus household bills
Stats NZ’s latest Consumer Price Index data available on 29 October 2026 showed prices rising 3.7% in the year to September 2026. The CPI tracks changes in a broad basket of goods and services. One household’s costs can rise faster or more slowly because each household buys a different mix of goods and services and devotes a different share of income to housing, transport and food.
Different measures answer different questions. The CPI helps describe price changes across the economy. Household living-cost indexes can show how inflation affects groups with different spending patterns. A rent listing, electricity bill or supermarket receipt is more useful for a household’s current decision. Recheck the source date whenever using an index in a longer-term budget.
Inflation can feel particularly sharp when essential costs rise together. A budget that once had a buffer may lose it through a higher rent renewal, vehicle repair and power bill in the same month. Keeping a small emergency reserve - even if it grows slowly - reduces the chance that one disruption leads to expensive borrowing.
The September 2026 CPI is useful as a price-pressure snapshot, not as a household budget. Prices overall rose 3.7% in the 12 months to that quarter, while particular expenses moved at very different rates. Petrol rose 19.1%, electricity 9.3%, and local-authority rates and payments 6.2%. An individual household’s exposure depends on fuel use, heating, region, housing and transport choices.
Region changes the mix of costs
Housing values and rents differ between major cities, regional centres and rural locations. Rural households may pay less for housing but more for transport, freight or specialist services. A smaller city may offer a shorter commute and lower parking costs, while reducing access to some jobs, schools or healthcare. Those trade-offs vary by neighbourhood.
MBIE’s regional economic tool provides indicators such as household income, rent and industry activity. Its figures can help compare broad regional patterns, though the measure and update date matter. A mean rent does not describe the property type, household size or tenancy conditions that a particular renter will encounter.
Families considering a move should compare a monthly budget and a weekly schedule. Include fuel, childcare availability, school transport, medical appointments, internet access and trips to see family. The cities and regions guide outlines how local transport and services shape daily life.
Make irregular bills visible
Many budgets underestimate expenses that arrive once or twice a year. Car registration, WOF checks, tyres, insurance, school stationery, uniforms, sports fees, dental treatment, holiday travel and gifts can all be predictable without being monthly. Divide an annual cost by the number of pay periods and move that amount into a separate savings category.
| Category | What to count | Hidden connection |
|---|---|---|
| Housing | Rent or mortgage, rates, body-corporate fees, insurance, maintenance | A lower rent can be offset by longer travel or poor insulation |
| Transport | Fuel, public transport, parking, servicing, registration, tyres and insurance | A car-dependent home can raise costs even when the property is cheaper |
| Power and communications | Electricity, gas, broadband, mobile plans and connection charges | Heating quality, household size and plan structure affect regular bills |
| Food and household goods | Groceries, lunches, cleaning products and pet supplies | Travel, storage, work schedules and dietary needs change the pattern |
| Health and care | Prescriptions, dental care, glasses, childcare and support services | Eligibility and availability differ; not every cost is subsidised |
| Irregular costs | School uniforms, repairs, gifts, travel, insurance excess and annual fees | Saving a small amount each pay period prevents a single bill becoming debt |
Car costs deserve a full estimate: purchase or finance, fuel, servicing, tyres, parking, insurance, registration and possible breakdowns. A vehicle used only occasionally may still carry fixed costs; a vehicle needed for work may protect income. Compare the cost of public transport and car-share access against the actual trips a household makes.
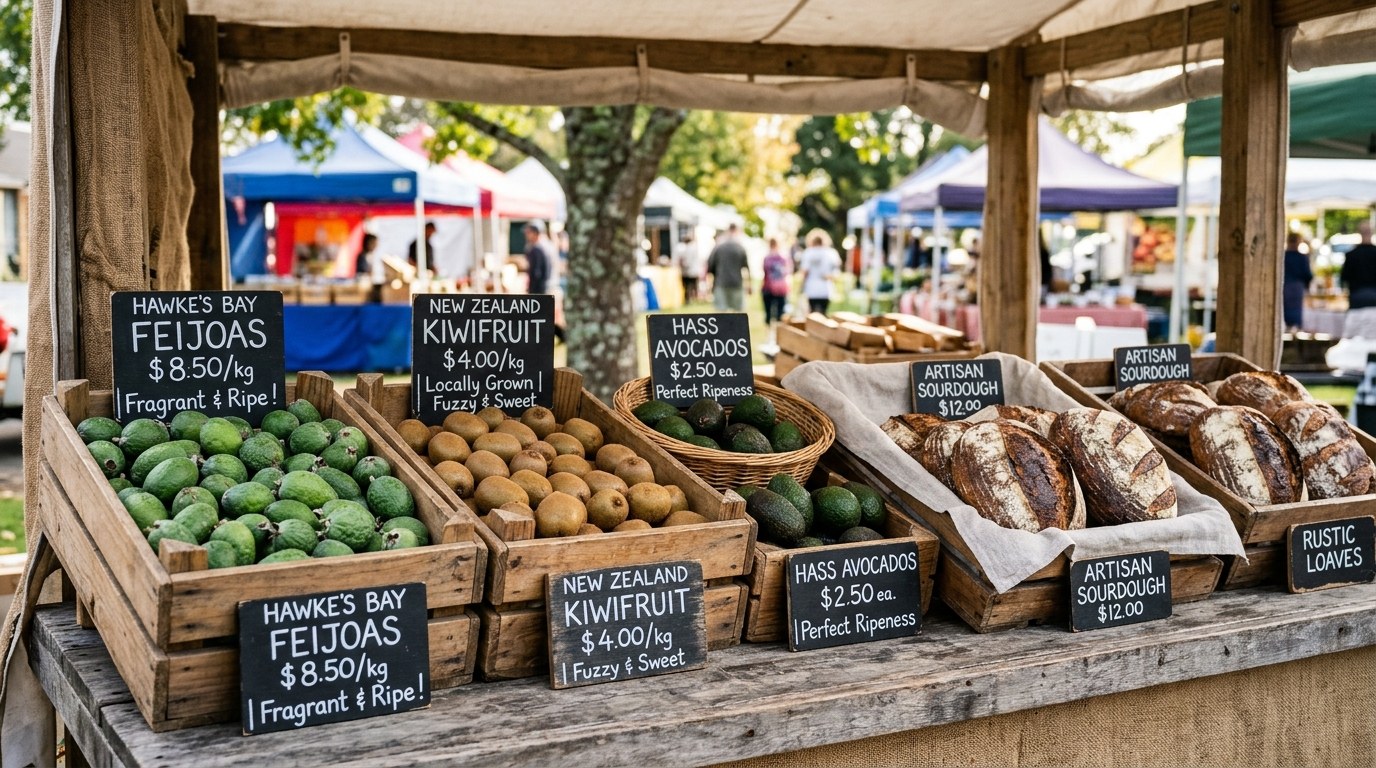
Food spending is easier to interpret with a simple meal plan and a few repeatable low-cost meals, but budgets should also reflect culture, dietary needs, work shifts and access to shops. A household that relies on one supermarket may have fewer practical choices than the national price comparison suggests.
Build a budget by pay cycle
- List take-home income by date, including irregular or seasonal pay.
- Record fixed bills and due dates before allocating flexible spending.
- Set aside a weekly share for annual and quarterly expenses.
- Track actual spending for several pay periods without judging each purchase.
- Choose one change that lowers pressure without damaging health, safety or work access.
- Review the plan after a rent change, new job, move, family change or interest-rate adjustment.
Weekly and fortnightly pay can make monthly bills awkward. A separate account for rent, power and annual expenses helps keep money for obligations from being absorbed into daily spending. A calendar reminder can also prevent late fees when the pay date moves around a public holiday.
A budget cannot close an income gap or make high housing costs affordable. It can show where pressure falls and help a household prepare for a conversation with a landlord, lender, employer or support service. A careful budget should not imply that every cost problem can be solved through personal discipline.
Get help before debt grows
Financial mentors and community services can help households understand debt, benefits, hardship arrangements and payment plans. A provider may also be able to offer a hardship process for a power, phone or lending account. The terms differ, so keep written records of conversations and confirm any new repayment amount against the household’s realistic income.
High-cost short-term credit can turn a temporary cash gap into a repeating cycle. Before borrowing, compare the total repayment, fees, missed-payment consequences and whether the payment will leave enough for essentials. A loan that funds food or power may be a sign the underlying budget has no room for a shock.
Employer assistance, Working for Families, Accommodation Supplement and other support can depend on income, household composition and eligibility rules. Check current official criteria instead of relying on an old calculator result or a friend’s situation.
Housing choices include ongoing risk
Renters should consider the bond, moving expenses, heating, moisture, insurance contents and the possibility of a rent increase at renewal. Home buyers should include rates, insurance, maintenance, mortgage changes, body-corporate costs and the reserve needed for repairs. A mortgage payment that fits the current income can still become difficult if interest rates or household earnings change.
Living with flatmates or extended family can reduce expenses, but it also creates questions about privacy, tenancy rights, utilities and responsibility for damage. A written agreement about bills and shared spaces can prevent a low-cost arrangement from becoming a source of conflict.